East Orange Uninsured Motorist Lawyer
What happens when the driver who hit you has no insurance, or not nearly enough? In many cases, the answer is a claim under your own auto policy, which changes who you deal with and how the claim moves forward.
It can feel unfair to turn to your own insurer for a crash someone else caused. Many drivers do not even know what limits they chose. Our East Orange uninsured motorist lawyers review your policy, present the claim, and push back when your insurer disputes it, with no fee unless we recover money.
Before you call your own adjuster back, talk with us for free.
What Happens in Your First Week With Our Firm?
Our father-and-son firm has represented injured people from East Orange since 1997. Uninsured motorist claims go more smoothly when the early steps happen fast, and here is what the first week usually looks like.
Day One
You talk with us in English, Spanish, or Haitian Creole, and we learn what happened, who was hurt, and which auto policies exist in your household. If you need care, we connect you with an established network of treating doctors, so treatment can start while we set up the claim.
The Next Few Days
 We notify the insurers involved, request the police report, and confirm whether the other driver truly had no coverage or just too little. We also review your own policy and any household policies for uninsured and underinsured motorist coverage.
As Your Claim Moves Forward
We review the available policies, explain important deadlines, and keep you informed as coverage questions are resolved. You will understand the steps we are taking and what information we still need.
Partners Richard Goldstein and Michael J. Goldstein bring more than five decades of combined experience, and Michael is a New Jersey Supreme Court Certified Civil Trial Attorney.
We advance case costs under our No Recovery, No Fee arrangement and handle uninsured motorist claims as part of our broader East Orange personal injury practice.
Is the Other Driver Uninsured or Underinsured?
The two terms sound alike but lead to different claims. The answer turns on whether the at-fault driver had any coverage at all, and if so, how it compares to your own policy. So the first step is confirming the other driver’s limits.
Uninsured
A driver is uninsured when there is no liability policy, or when their insurer denies coverage for the crash. That can happen when the policy lapsed for nonpayment or the driver was excluded. A hit-and-run driver who cannot be identified counts as uninsured too.
Underinsured
 Under New Jersey law, a driver is underinsured only when their liability limits are lower than the underinsured motorist limits on your policy. The comparison is between the two policies, not between the other driver’s coverage and what your injuries are worth.
Lapsed, Canceled, and Excluded Coverage
Some drivers believe they are insured until their carrier reports a lapse for nonpayment or an exclusion. A denial like that can turn an apparently insured driver into an uninsured one. It may be worth challenging while the UM claim moves forward.
Drivers From Out of State
East Orange sits along routes used by drivers from New York, Pennsylvania, and beyond, and confirming an out-of-state driver’s coverage can take time. If it cannot be verified, notifying your own insurer early keeps the UM option open while the facts are sorted out.
How Does the Limits-to-Limits Comparison Work?
The Appellate Division confirmed the limits-to-limits approach in a 2021 decision, and it surprises many drivers. Here is how different combinations play out.
| At-fault driver’s liability limit | Your UIM limit | General result |
|---|---|---|
| $35,000 | $35,000 | Not underinsured, so no UIM claim |
| $35,000 | $100,000 | Underinsured, with up to $65,000 more available after credit for the $35,000 |
| $50,000 | $250,000 | Underinsured, with up to $200,000 more available after credit |
| $250,000 | $100,000 | Not underinsured, because the other driver’s limit is higher |
Once UIM coverage applies, the amount available generally reflects a credit for the at-fault driver’s applicable liability limits, even if the injured person settles for less than those limits.
In practice, the UIM limit you chose when you bought your policy can matter more than anything the other driver carries.
Where Can UM Coverage Come From in Your Household?
Whether you have UM or UIM coverage depends on the type of policy you or a household relative bought and the limits that were chosen. The state’s auto insurance buyer’s guide explains the options.
| Your household situation | Where UM or UIM coverage may come from |
|---|---|
| You own and insure a car on a standard policy | Your own policy, up to the limits you selected |
| You live with a relative who insures a car | That relative’s policy, based on its terms |
| You were a passenger in someone else’s car | The policy covering that car, and possibly your household policy |
| You carry a basic policy | UM coverage may not be included, so other sources need to be explored |
| No one in your household has auto insurance | Possibly the state’s Unsatisfied Claim and Judgment Fund, if you qualify |
New Jersey generally does not let you stack UM or UIM coverage from several policies, so the task is finding the one policy that applies and how much it provides. For uninsured pedestrians, the 2026 Boone decision explains how the state fund and rideshare policies can also come into play.
Rideshare and Work Vehicles
If you were riding in an Uber or Lyft, or driving for work, when an uninsured or underinsured driver hit you, the rideshare policy or an employer’s commercial policy may add coverage. Knowing why you were on the road that day can open coverage beyond your personal policy.
Why Does a Claim Against Your Own Insurer Feel Different?
Many people are caught off guard by how adversarial a UM or UIM claim can get. The insurer you have paid for years now evaluates your injuries the way an opposing insurer would.
Even though you pay premiums to the company, its adjuster may challenge your injuries, question fault, or dispute the amount of compensation available under your policy.
At the same time, your insurer owes you duties a stranger’s insurer does not, including fair handling of the claim under your policy. The relationship runs both ways, because your policy also requires you to cooperate, give notice, and follow certain steps.
What Must You Do Before Accepting the At-Fault Driver’s Limits?
In an underinsured claim, the order of steps matters as much as the amounts. Settling with the at-fault driver too early, or without notice, can put your UIM coverage at risk.
- Confirm the at-fault driver’s liability limits in writing.
- Tell your own insurer about the possible UIM claim and about any offer from the at-fault driver’s insurer.
- Give your insurer the chance to respond to that offer before you accept it.
- Accept the at-fault limits only after that process is complete.
- Present the UIM claim with full medical, wage, and liability documentation.
What Documents Help Support a UM or UIM Claim?
 Because the claim is made under your own policy, you and your household often already hold many of the documents that matter. Gathering them early saves time later, and we can request anything you cannot find.
- The declarations page for your auto policy and any household relative’s policy.
- The police report and any written denial of coverage from the other driver’s insurer.
- Medical records and bills, including PIP payment statements.
- Pay stubs, tax returns, or employer letters showing time missed from work.
- Photos of the vehicles, the scene, and your injuries.
What Happens When Your Own Insurer Disputes the Claim?
In a UM or UIM claim, your insurer steps into the at-fault driver’s shoes. It can dispute how the crash happened, how badly you were hurt, and what the claim is worth, just as the other driver’s insurer would have.
Arbitration Is Common
Many New Jersey auto policies send UM and UIM disputes to arbitration rather than a jury. We prepare every claim as if a neutral decision-maker will review each record. That approach tends to produce better results, and it keeps the claim ready if it moves to court.
Cooperation Requests
Your insurer may ask for a recorded statement, medical authorizations, or an examination under the policy’s cooperation terms. Some of those requests are required and some can be narrowed, so review them with us before you respond.
When Your Insurer Delays
Insurers owe their policyholders fair treatment, and New Jersey law provides remedies in some situations when an insurer unreasonably delays or denies a valid UM or UIM claim. Whether those remedies apply turns on the facts, so we document each step of the insurer’s handling from day one.
Shared Fault and the Lawsuit Option
Your insurer can argue you were partly to blame, and under New Jersey’s comparative negligence statute any share assigned to you reduces the claim. The limitation on lawsuit option on your policy can also affect the non-economic part of the claim.
What if a Hit-and-Run Driver Was Involved?
A driver who flees and is never identified is treated as uninsured. New Jersey does not require physical contact with the unidentified vehicle for a UM claim, as courts applying the state’s statute have recognized. Report the crash promptly to police and to your own insurer, and keep any photos of debris or a partial plate number.
Our Newark hit and run page covers more of those cases, including the evidence that can identify a driver who left.
Pedestrians and Cyclists Hit by Uninsured Drivers
People on foot or on bicycles hit by uninsured drivers may be able to claim UM benefits through their own or a household relative’s auto policy, even though they were not in a car. When no household policy exists, the claim may need to look elsewhere. That is where the state fund and the facts of the crash become important.
FAQs About Uninsured Motorist Claims in East Orange
Will filing a UM claim raise my insurance rates?
Whether a New Jersey insurer can raise rates after a UM or UIM claim depends on fault and the insurer’s rating rules. Claims for crashes you did not cause are generally treated differently from at-fault crashes, and your policy terms help answer the question.
What if I only have a basic auto policy?
A New Jersey basic auto policy may not include uninsured motorist coverage, which can limit recovery after a crash with an uninsured driver. Other household policies or the state’s Unsatisfied Claim and Judgment Fund may still be worth exploring.
How long do I have to bring a UM claim?
UM and UIM claims in New Jersey are contract claims against your own insurer. Their deadlines can differ from the two-year limit for suing the at-fault driver. Your policy’s notice requirements also apply, so it is safest to act promptly.
What if the other driver gave me fake insurance information?
When a New Jersey driver’s insurance information turns out to be invalid, the claim may proceed as an uninsured motorist claim. Report the crash promptly and keep copies of whatever the driver gave you.
Can I also sue the uninsured driver personally?
You can generally sue an uninsured New Jersey driver personally, but collecting from someone without insurance is often difficult. UM coverage is usually the practical source of recovery, and a personal claim makes sense only in some cases.
Contact Our East Orange Uninsured Motorist Lawyers
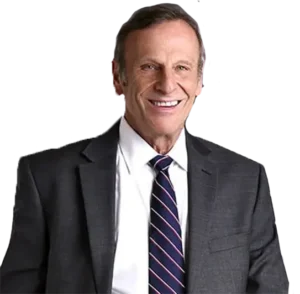
Richard Goldstein, East Orange Uninsured Motorist Lawyer
You paid for this coverage so that someone else’s lapse would not become your burden. Start by finding the declarations page for your auto policy and any household policies.
Those pages list your uninsured and underinsured motorist limits, and those numbers often shape the entire claim.
Our attorneys can review those limits with you at no charge. Contact our office and we will start by reviewing every policy that may cover you. UM claims also sit within our broader East Orange car accident practice.
Results depend on the specific facts of each case, and past outcomes do not predict future results.